UK house prices fall 0.6%, Nationwide flags strain on buyers
UK house prices fell 0.6% in May, the first monthly drop this year, as higher mortgage costs linked to the Iran war squeezed buyers, Nationwide said, with…
Hazal Anyalı ·
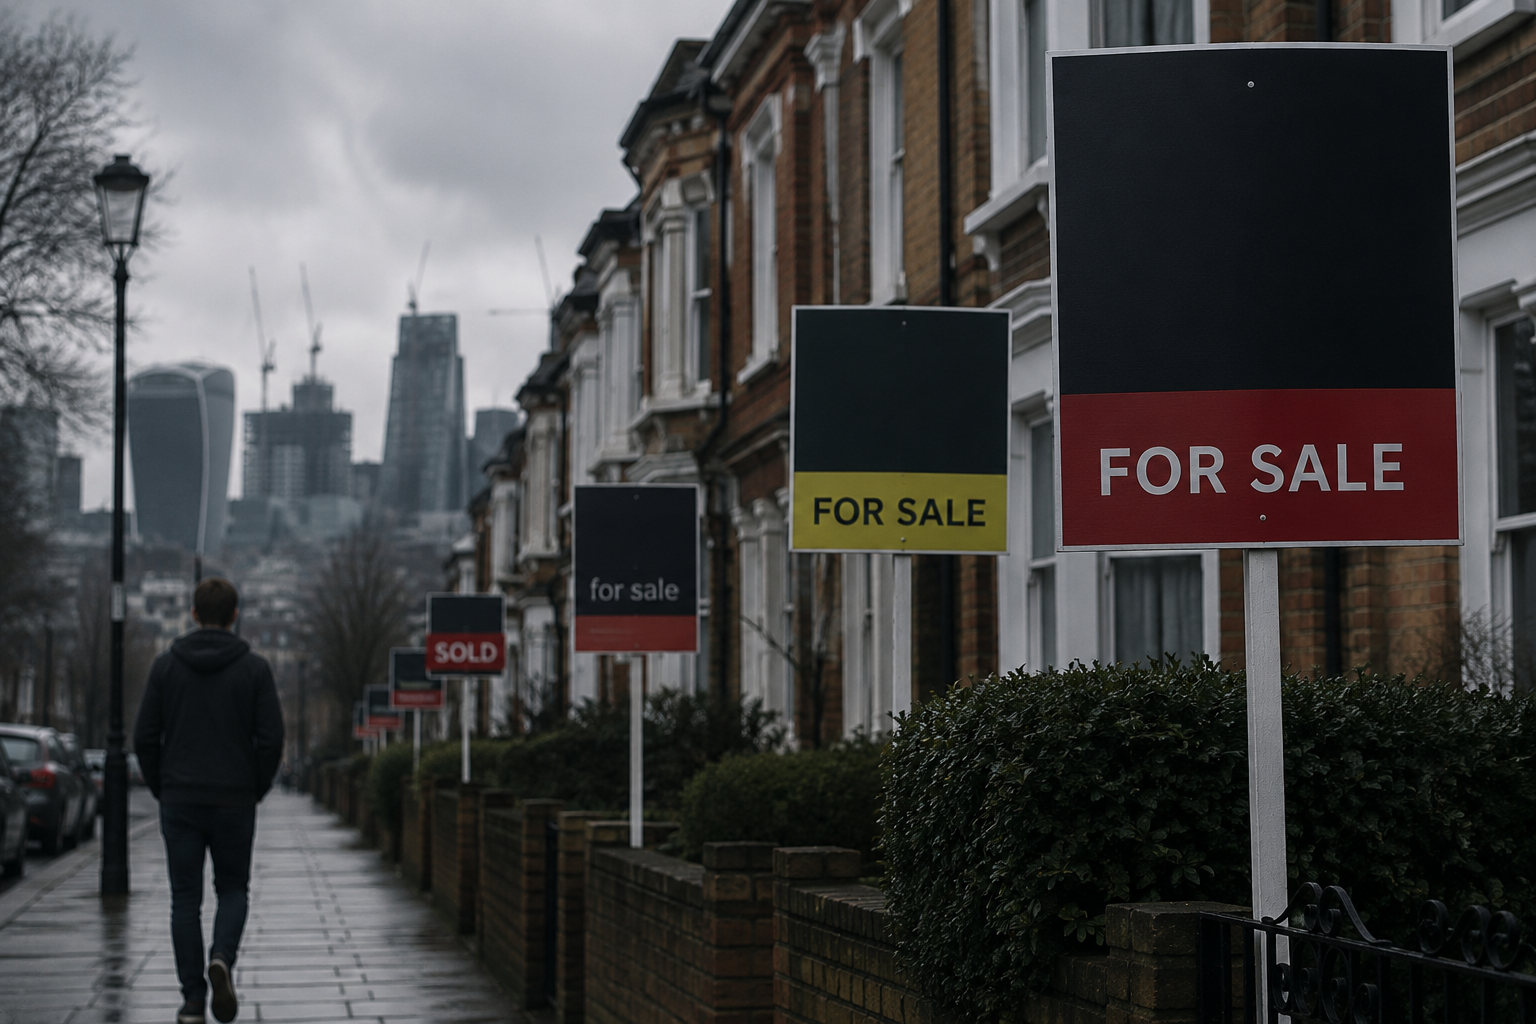
UK house prices fell 0.6% in May, the first drop this year, as mortgage costs tied to Iran war squeezed buyers, Nationwide said. Two-year fixes are 5.68%.
Nationwide Building Society reported the steepest monthly decline in almost a year. The typical property now stands at £278,024 ($374,400), a larger fall than the 0.2% economists had penciled in.
Despite the monthly setback, values were still 1.7% higher than a year earlier. The reversal marks the first monthly slip of the year, underscoring a loss of momentum.
Rates bite after geopolitics jolt borrowing costs
Mortgage rates have eased from recent peaks, but not enough to rebuild confidence. Moneyfacts put the average two-year fixed deal at 5.68%, nearly 0.9 percentage points above late February levels.
That timing matters: the increase followed the escalation tied to the Iran war, after the US and Israel attacked Iran. Higher funding costs are filtering through to would-be buyers, trimming what they can afford.
In practical terms, the strain shows up in smaller budgets and longer decision times. From starter flats in outer zones to family homes in commuter belts, pricier loans narrow choices.
Forecasts miss as household cushion thins
The 0.6% slide overshot consensus for a modest 0.2% decline. Earlier this year, solid household balance sheets helped the market absorb shocks, but that support looks thinner now.
Wage growth is barely keeping pace with inflation, limiting breathing room. As fixed-rate deals expire, more borrowers face refinancing at higher rates, reinforcing the affordability squeeze.
Nationwide’s figures arrive as approvals and new listings remain sensitive to rate moves. Even small shifts in borrowing costs can change monthly payments by meaningful amounts.
Market pulse: what holds and what gives
For sellers, pricing power may depend on segment and location. Well-priced homes still move, but buyers are more cautious, and chains can take longer to knit together.
For buyers, the headline is simple: higher mortgage rates reduce maximum loan sizes. That pushes some to delay, downsize, or look farther out along rail and bus corridors.
Next steps hinge on the path of rates, inflation, and pay. If borrowing costs stabilize or retreat, activity could firm; if not, the pressure outlined in May’s drop may persist into summer.