Washington Weighs China Supply Risk as Shanghai Furniture Shows Draw 180,448
Chinese trade-show organizers reported record overseas attendance at two Shanghai furniture fairs, offering Washington another data point in its supply-chain…
Lauren Collins ·
Washington Weighs China Supply Risk as Shanghai Furniture Shows Draw 180,448
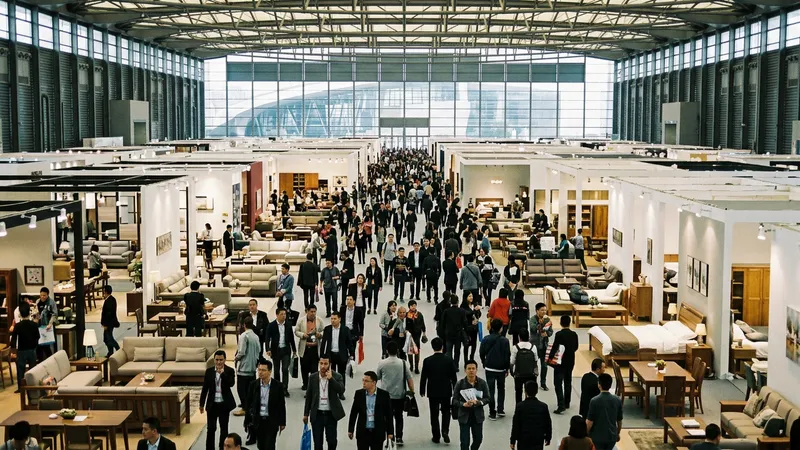
Washington’s China supply-chain debate gained a fresh commercial data point on September 29, 2026, after CNFA and IM Sinoexpo said their Shanghai furniture exhibitions recorded 180,448 visits. The organizers said 37,394 of those were overseas visits, a record that points to China’s continuing pull as a manufacturing and sourcing hub even as U.S. officials press companies to reduce concentrated exposure.
The figures came from Furniture China and Maison Shanghai, five-day events held in Pudong, Shanghai, across two venues. For U.S. policymakers, the headline is not furniture alone; it is the persistence of buyer traffic into Chinese trade platforms at a time when the White House, Congress and federal agencies are trying to make global supply chains less vulnerable to coercion, pandemic-style disruption and geopolitical shocks.
CNFA and IM Sinoexpo organized the Furniture China and Maison Shanghai events, which serve exporters, manufacturers, designers and global buyers in the home-furnishings supply chain. The organizers described the 2026 edition as spanning five days and two major venues, with total visits and overseas attendance used as measures of commercial reach.
Those numbers matter in Washington because trade fairs are one way China converts factory capacity into international orders. They bring buyers, suppliers and logistics networks into the same ecosystem, lowering search costs for companies that want to source finished goods, components, design services or production capacity.
Washington Weighs China Supply
The U.S. policy debate has moved well beyond tariffs. The White House and National Security Council frame resilience as a strategic issue; the Commerce Department handles export controls and industrial programs; the Treasury Department watches financial channels; and Congress shapes subsidies, procurement rules and China-related restrictions. In that environment, a trade-show attendance figure can become evidence in a larger argument about whether diversification is happening in practice or mainly in speeches.
The 180,448 visits reported by the organizers do not show how many contracts were signed, how much merchandise will be exported or how many U.S. companies attended. The 37,394 overseas visits also do not identify countries of origin. Those limits matter: visits are a signal of interest, not a verified measure of trade flows.
Still, the overseas figure is useful because it suggests foreign buyers continue to treat Shanghai as a place to compare suppliers and products at scale. If buyers keep coming, Chinese manufacturers retain a channel for defending market share even when U.S. and allied governments encourage firms to add suppliers in Mexico, Southeast Asia, India or domestic markets.
For U.S. retailers and manufacturers, the commercial calculation is narrower than the geopolitical one. China’s advantages often include dense supplier networks, flexible production runs and established shipping relationships. Diversification can reduce political risk, but it can also raise costs, complicate quality control and require new financing or inventory buffers.
That tension is what makes the Shanghai numbers politically relevant. A company may agree with Washington that concentration risk is too high while still buying from Chinese suppliers because alternate factories cannot match price, volume or delivery reliability. Policymakers can subsidize new capacity, but firms will test those policies against margins and lead times.
The furniture sector is not usually treated as a national-security industry in the way semiconductors, batteries, critical minerals or advanced telecommunications are. But it is part of the broader consumer-goods supply chain that shapes shipping demand, warehousing, retail pricing and small-business sourcing decisions. If China remains central in lower-technology sectors, Washington’s partial decoupling strategy becomes more complex: restrictions may tighten around strategic goods while broad commercial dependence persists elsewhere.
Beijing has an interest in presenting trade fairs as proof that foreign buyers still value Chinese production. U.S. officials have the opposite incentive when arguing for industrial policy and supply-chain mapping: they need to show that dependence on China remains large enough to justify continued intervention. The same attendance figure can therefore support competing narratives.
The missing detail is the corporate response. If U.S. buyers attended in force, the event would suggest that cost and supplier density are still outweighing political pressure in many purchasing decisions.
If the overseas traffic came mainly from non-U.S. markets, the number would point to a different pattern: China preserving export links even as the U.S. market becomes more politically contested.
A Washington reading also separates resilience from decoupling. Resilience means firms can withstand a shock by adding supplier options, holding more inventory or moving some production closer to end markets. Decoupling means a deeper break in commercial ties. The Shanghai figures, as reported by the organizers, are more consistent with a world of selective diversification than a clean split.
The global macro effect runs through trade volumes, shipping demand and inflation. If China keeps attracting overseas buyers while U.S. and allied firms add backup suppliers elsewhere, the world may end up with duplicated capacity and higher redundancy costs rather than a rapid shift away from China. If buyers instead move orders at scale, Chinese exporters would face margin pressure, while newer production hubs could see stronger investment and infrastructure demand.
For CNFA and IM Sinoexpo, the near-term benefit is reputational. A record overseas attendance number strengthens the case for Shanghai as a meeting point for the industry and gives exhibitors a marketing tool. For the wider furniture and home-goods sector, it may reinforce the view that China remains difficult to replace, even where companies want a second or third sourcing base.
By November 30, 2026, the useful test is whether Washington turns this kind of expo data into policy language or whether it stays inside trade promotion. The thesis is strengthened if U.S. officials cite China’s trade-fair pull as evidence of persistent supply-chain concentration, or if U.S. firms announce supplier diversification while maintaining cost and quality targets. It is weakened if the Shanghai attendance figures draw no policy response, or if companies talk about decoupling without making measurable sourcing changes.