Fed doubts hit Asian stocks as Treasury yields surge higher
Asian stocks faced pressure after a Wall Street technology selloff, higher long-dated Treasury yields and unclear Federal Reserve rate signals.
Mei Lin ·
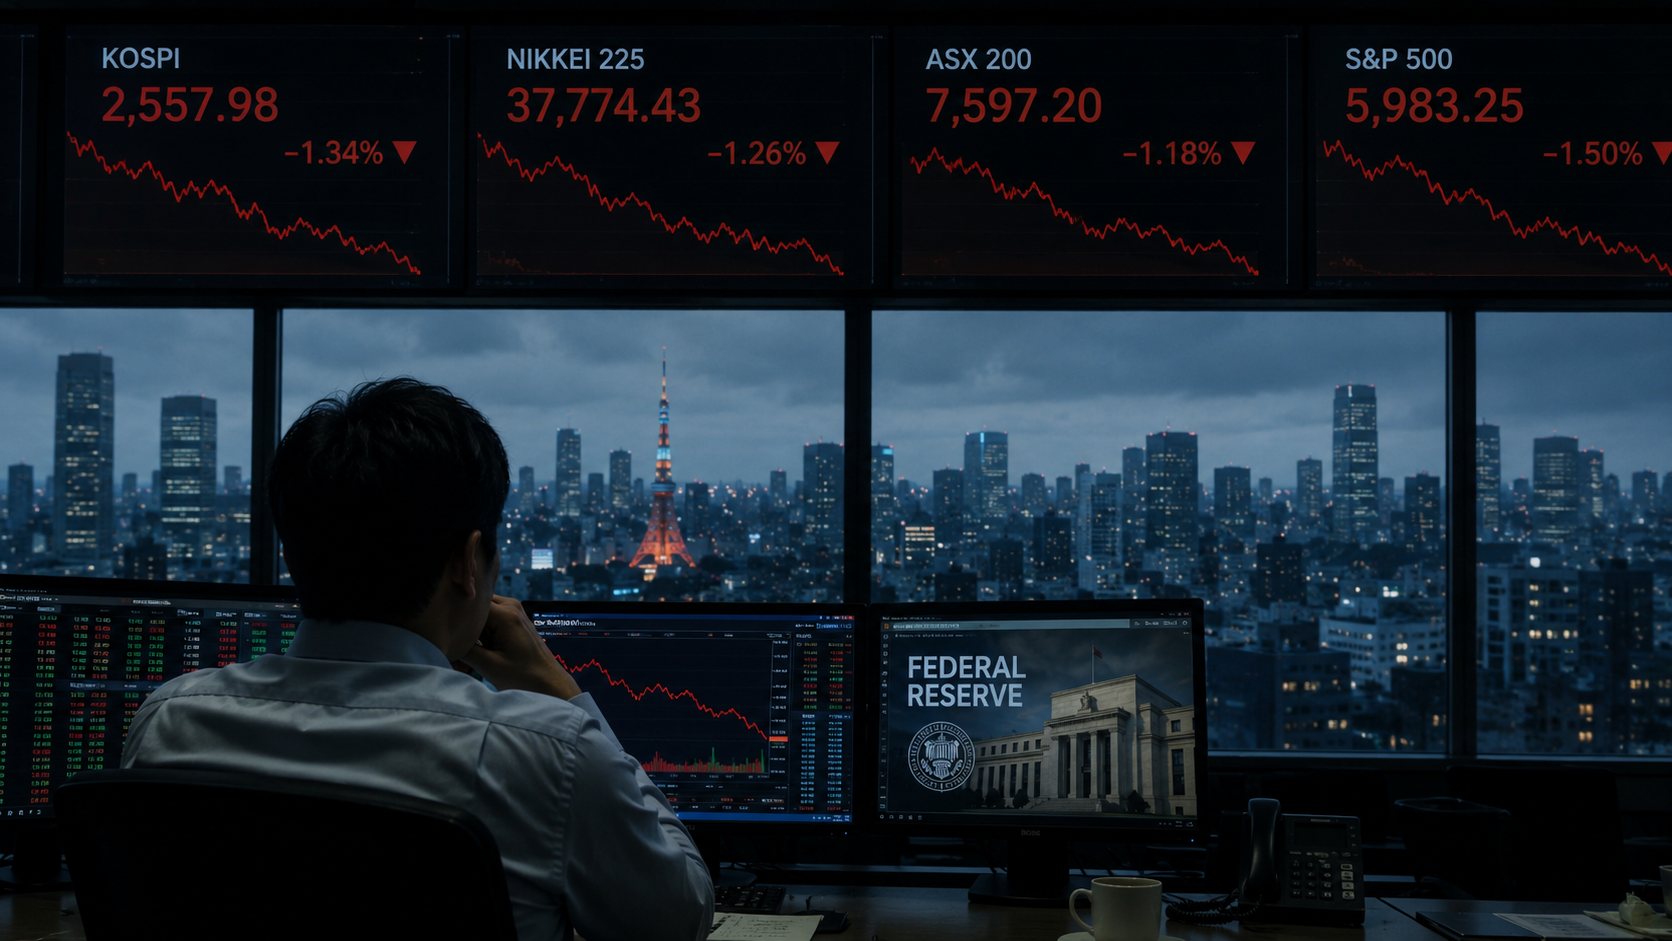
Asian stocks faced a weaker open after U.S. tech shares fell, Treasury yields surged, and Fed signals kept rate expectations unsettled.
Equity-index futures in Australia, Japan and South Korea pointed to early losses, extending pressure from a U.S. session dominated by technology selling. The moves put Asia on course to absorb a sharp repricing across equities, bonds and currencies after investors questioned the payoff from heavy artificial intelligence spending.
Long yields reset the tone
The bond market delivered the clearest warning sign after the Federal Reserve left interest rates unchanged. Longer-dated Treasury yields climbed while short-term yields fell, steepening the curve and showing a split between inflation worries and policy-rate expectations.
The 30-year Treasury yield rose more than 10 basis points to its highest level since 2007, according to the market data cited in the source material. The 10-year yield increased five basis points to 4.66%, while the two-year yield dropped six basis points to 4.23%.
That pattern matters because the two-year note usually tracks expectations for central bank policy more closely, while the 10-year and 30-year maturities carry more of the market’s view on inflation, growth and fiscal risk. The dollar also posted its biggest decline in two weeks, adding a currency-market layer to the shift in global risk pricing.
Chipmakers carry the pressure
U.S. equities supplied the immediate trigger for Asia’s weaker setup. The S&P 500 fell 1.5%, with chipmakers leading the decline as investors reassessed whether AI-related capital expenditure can keep supporting valuations.
The Nasdaq 100 moved into correction territory after falling 11% from its record high, based on the index moves in the source material. That retreat is important for Asian markets because large technology hardware, semiconductor and supplier names across the region often trade in line with U.S. chip and cloud-computing sentiment.
Company news after the close gave investors a mixed read. Meta Platforms Inc. issued a muted forecast, while Microsoft Corp. reported its fastest cloud-computing growth in four years, a result that helped lift U.S. stock futures during early Asian trading.
The contrast between the two companies sharpens the market’s central debate. If cloud demand keeps expanding fast enough to justify AI infrastructure spending, the selloff may stay concentrated in companies where expectations have run ahead of earnings; if forecasts keep softening, the pressure can spread across the broader technology supply chain.
Fed split adds inflation risk
Fed Chair Kevin Warsh said holding rates steady did not reflect policy inertia at the central bank, according to the remarks in the source material. He also said markets would be free to respond to incoming economic signals rather than rely on a preset path from policymakers.
The decision was not unanimous. Three of the Fed’s 12 voting officials dissented in favor of a rate increase, showing that inflation concerns remain strong enough inside the central bank to challenge expectations for easier policy.
That split leaves investors with two competing messages. A steady policy rate suggests officials are not rushing to tighten further, but the dissents and jump in long yields show the market is still pricing a risk that inflation may not fall quickly enough.
Three paths for markets
If AI spending concerns remain the main driver, global macro pressure would likely come through weaker equity risk appetite rather than an immediate policy shock. Meta would stay under scrutiny because its forecast is now part of the valuation debate, while the wider semiconductor and cloud infrastructure sector would face tougher demands for proof of revenue conversion.
If Microsoft’s cloud growth becomes the stronger signal, the market mechanism changes. Global risk appetite could stabilize, Microsoft would reinforce the case for continued enterprise cloud demand, and Asian suppliers tied to data centers, chips and equipment could regain support.
If the Fed’s inflation split becomes the dominant force, bond yields would set the market’s direction. Higher long-dated yields would tighten financial conditions globally, weigh on rate-sensitive growth stocks, and put pressure on Asian equity benchmarks even if company earnings remain sound.
The open questions are specific: whether Treasury yields keep rising, whether chipmakers find buyers after the Nasdaq 100’s correction, and whether upcoming company guidance confirms or weakens the AI spending case. For now, Asian markets are starting from a position shaped less by local news than by a U.S. repricing of technology, duration and central bank credibility.