Why Nike Is Losing Market Share to On and Hoka—and What Happens Next
Atlas Newsdesk ·
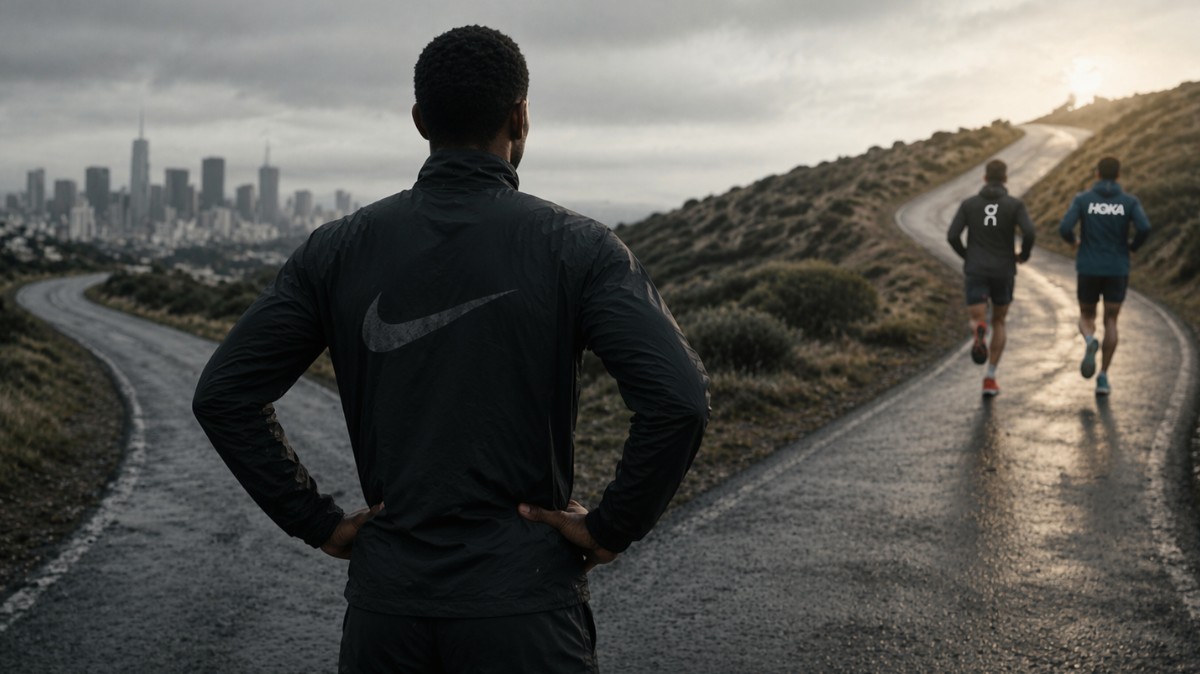
For much of the past generation, Nike represented something close to a corporate inevitability. Its dominance in athletic wear was not merely a function of scale, but of structural advantage: a brand rooted in performance credibility that could extend seamlessly into lifestyle, culture, and mass distribution without dilution.
That model is now under sustained pressure.
Nike’s financial performance reflects this shift. Growth has slowed materially, margins have compressed, and the company is operating far below its prior earnings peak. More tellingly, the competitive landscape has evolved in ways that challenge Nike’s historical positioning. What was once a fragmented field of smaller competitors has become a more sophisticated ecosystem of focused, premium challengers.
The question facing Nike today is not simply how to recover lost momentum, but whether it can reassert the strategic coherence that once made it dominant.
A Market That Continued Growing—Without Nike Leading It
The broader market context underscores the issue. Athletic footwear, particularly running, remains a structurally attractive category. The global running shoe market is projected to grow steadily, reaching upwards of $80 billion over the next decade, supported by rising participation in fitness and ongoing product innovation.
In other words, Nike’s challenges are not occurring in a declining market. They are occurring in a market that continues to expand.
This distinction is critical. It suggests that Nike’s relative underperformance is not cyclical or macro-driven, but competitive and strategic.
The Rise of Focused Competitors
Over the past five years, challenger brands have not only gained visibility—they have meaningfully outperformed incumbents.
Between 2021 and 2023, emerging players such as On Running and Hoka grew revenues by roughly 29% , compared to approximately 8% growth for legacy brands.
Individually, their trajectories are even more striking:
- On Running has scaled rapidly into a multi-billion-dollar business, driven by strong growth in both performance and lifestyle segments.
- Hoka, owned by Deckers, continues to deliver double-digit growth, with recent quarterly revenues exceeding $650 million and expanding globally at pace.
What differentiates these companies is not simply product innovation, but strategic discipline.
They have:
- Focused narrowly on performance categories (particularly running)
- Built credibility with core users before expanding
- Maintained tighter control over distribution and pricing
This stands in contrast to Nike’s broader, more diffuse positioning in recent years.
Importantly, these brands have captured disproportionate mindshare among higher-income consumers and specialty retail channels—segments that historically reinforced Nike’s premium perception.
Nike’s Competitive Position: From Category Leader to One of Many
Nike remains the largest player in the athletic footwear market, but its relative positioning has shifted.
Where Nike once defined the performance standard, it now competes in categories where:
- Innovation is more distributed
- Consumer loyalty is more fragmented
- Brand leadership is less concentrated
The running category illustrates this dynamic clearly. Once a core pillar of Nike’s credibility, it is now an area where competitors have established strong footholds. Indeed, Nike has acknowledged losing share in running to newer entrants and is actively attempting to rebuild its presence through product redesigns and increased focus.
This is not a marginal issue. Running is one of the most structurally important segments in athletic wear, both for revenue and for brand authenticity.
Losing leadership here has second-order effects across the entire portfolio.
Leadership Response: Acknowledgment and Early Course Correction
Nike’s current leadership appears increasingly aware of these challenges.
CEO Elliott Hill, who returned to lead the company, has initiated a series of strategic adjustments aimed at restoring product innovation and accelerating development cycles. Recent leadership changes within the innovation function underscore the urgency of this effort, as Nike seeks to reinvigorate its pipeline amid intensifying competition.
At the product level, Nike has begun to re-emphasize performance categories, particularly running. Redesigned models such as the Pegasus and Vomero have contributed to a notable rebound in that segment, with reported growth of approximately 20% in recent periods.
Management has also signaled a shift in distribution strategy. After aggressively prioritizing direct-to-consumer channels, Nike is re-engaging with wholesale partners to regain shelf space and broaden reach. This reflects a more balanced approach, though it introduces trade-offs in terms of brand control and margin structure.
Taken together, these actions suggest a recognition that prior strategic choices—particularly around product focus and distribution—require recalibration.
Why a Turnaround Is Possible
Despite the challenges, a credible turnaround case exists.
First, Nike retains structural advantages that are difficult to replicate:
- Global scale and supply chain capabilities
- Deep relationships with athletes, leagues, and retailers
- Unmatched brand awareness
Second, the company’s recent product initiatives indicate that innovation has not disappeared—it has been deprioritized. Early traction in running suggests that renewed focus can yield results.
Third, the competitive landscape, while more challenging, is not static. Even high-growth challengers are beginning to face their own constraints. For example, Hoka’s growth has shown signs of moderation from earlier peaks, raising questions about the sustainability of its trajectory.
Finally, Nike’s breadth remains a differentiator. Unlike more specialized competitors, it has the ability to operate across multiple categories, price points, and geographies. If properly managed, this can once again become an advantage rather than a liability.
Why a Turnaround Will Be Difficult
However, the path forward is neither quick nor assured.
Rebuilding performance credibility requires sustained investment in product innovation, athlete partnerships, and marketing. These investments will weigh on margins in the near term.
At the same time, Nike must address structural issues in its distribution and pricing strategy. Restoring a premium brand perception likely entails reducing promotional activity and tightening channel control—actions that may constrain short-term revenue.
There is also the challenge of consumer perception. Brand positioning, once diluted, cannot be reset immediately. It requires consistent execution over multiple product cycles.
In this sense, Nike’s situation is less a typical corporate turnaround and more a process of brand reconstruction.
Conclusion: A Test of Strategic Discipline
Nike is not in decline in the conventional sense. It remains a highly profitable, globally dominant company operating in a growing market.
But it is no longer operating from a position of uncontested leadership.
The emergence of focused competitors, combined with Nike’s own strategic drift toward fashion and volume, has eroded key elements of its historical advantage. The company now faces a more complex environment, one in which its traditional model is harder to sustain.
The turnaround path is clear in principle: return to performance, restore brand discipline, and rebuild pricing power.
The challenge lies in execution.
Nike must demonstrate that it is willing to sacrifice short-term growth to regain long-term positioning. That requires not only strategic clarity, but organizational discipline—something that has been less evident in recent years.
Whether Nike succeeds will depend less on market conditions and more on its ability to rediscover the focus that once made it exceptional.