

Tax uncertainty complicates Roth conversions for retirees
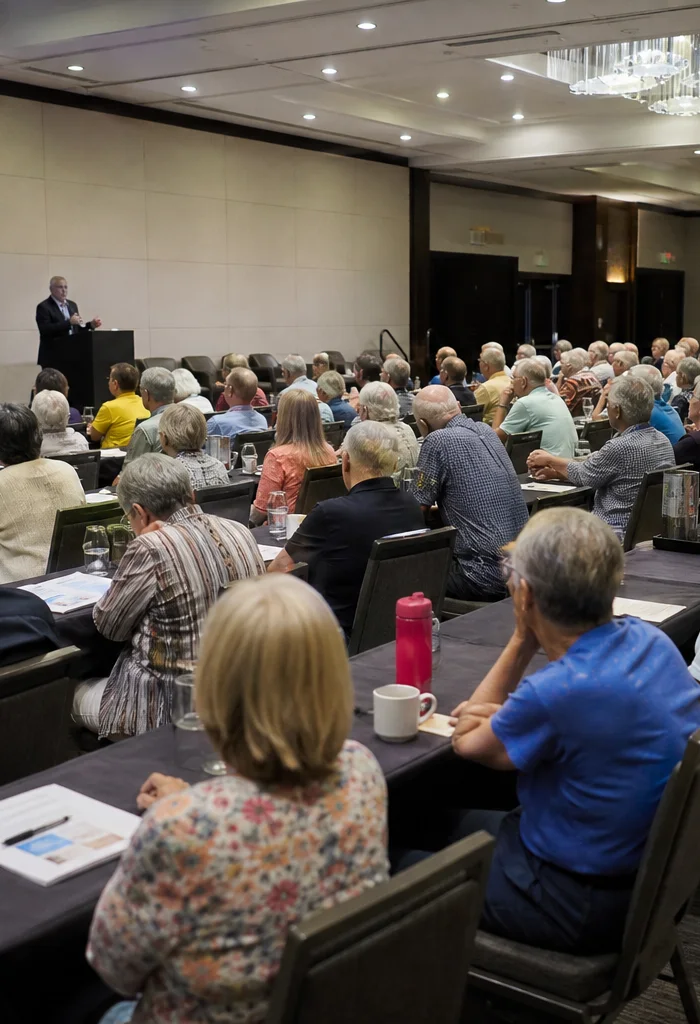
Bogleheads weighed Roth conversions and retirement-account errors at a Las Vegas gathering, highlighting tax risks for long-term savers.
Tax columnist Laura Saunders described confusion over retirement-account terminology and inheritance rules in her November 20, 2026, account of the conference. Her reporting focused on investors committed to inexpensive, long-term investing, illustrating that familiarity with portfolio strategy does not necessarily extend to tax administration.
Roth decisions depend on future taxes
The central Roth decision involves comparing the tax cost today with the rate that would apply to future withdrawals, Saunders explained. Roth contributions use money already taxed, while distributions generally escape taxation; converting traditional retirement savings therefore requires weighing an immediate liability against potential future benefits.
Under that framework, a conversion is more attractive if the applicable marginal rate today is below the rate a saver would otherwise face when withdrawing traditional retirement funds. If the relationship reverses, paying the tax earlier becomes less appealing. Those are conditional comparisons, not a recommendation that every investor should convert.
Congress adds an uncertainty that individual calculations cannot resolve: future lawmakers might alter Roth treatment or impose restrictions, Saunders wrote. Her account also identified a competing consideration for policymakers, since conversions bring forward federal tax receipts. It described no specific legislative proposal to change the rules.
Timing remains within the investor’s control even when legislation does not. Saunders identified converting shortly before relocating somewhere with lower taxes as a potentially inefficient choice, and recounted a retiree who asked about a backdoor Roth strategy when he actually meant a conventional conversion of existing traditional IRA savings.
Beneficiary paperwork carries financial consequences
Retirement-account consultant Denise Appleby described a separate danger: instructions that fail to produce the intended legal or administrative result. In one example she cited, a divorced account holder’s unsuccessful attempt to replace his former spouse as beneficiary left her inheriting approximately $320,000 from his 401(k).
Appleby . Her warning places follow-through alongside the initial instruction: “Just because you give instructions to a custodian doesn’t mean they’re carried out correctly,” Appleby said. “Be sure to follow up.”
Saunders also reported encountering an investor who incorrectly associated Roth accounts with the basis adjustment available for certain inherited taxable assets. Her explanation distinguished that capital-gains treatment from retirement-account rules, a distinction relevant to decisions about inheritance and charitable giving.
Bogle principles meet tax complexity
The Bogleheads take their name from Vanguard Group founder John “Jack” Bogle and favor passive funds with low expenses. Their conference is sponsored by the nonprofit John C. Bogle Center for Financial Literacy; the Bogleheads.org discussion forum operates separately from that organization.
Sean Mullaney, a Los Angeles CPA and financial planner who spoke at the gathering, cautioned against reorganizing personal choices solely around tax advantages. He advised against starting a business for deductions or relocating exclusively to reduce state taxes, arguing that sound planning generally should not require extensive portfolio changes.
For savers considering a conversion or account transfer, the conference discussions separated two decisions: whether a transaction suits their tax circumstances and whether its execution matches their instructions. Future congressional treatment remains unresolved; Appleby’s practical recommendation was to verify completion rather than assume that submitting paperwork finishes the job.
More stories
- Fidelity bars Anthropic IPO flippers for six months
- Three-bucket strategy reduces retirement stock-sale pressure
- US 30-year mortgage APR falls 14bp to 7.24%
- Congress clears 25-business-day holds for vulnerable investors
- 30-year mortgage APR falls 8bp to 7.19%
- Vehicle service contracts can cost several thousand dollars a year
Latest news
- Paul seeks 20%-30% federal credit for U.S. film shoots
- Liberia seeks bigger US exports as AGOA runs to 2028
- SAF-RSF fighting worsens 10-year oil pollution crisis, groups say
- Rwanda women-owned exports fall 51% from 2021 peak
- Strictly expands stage for 8 couples in Blackpool return
- Spain opens 200m-voter test for Europe's right
- Saudi event season faces EASA airspace warning to Jan. 31
- EU housing costs outpace incomes after home prices rise 70%