Global stocks slide to four-month low as Middle East oil supply risks surge
Global stocks hit a four-month low on March 23, 2026 as Middle East tensions and an oil surge revived concerns about inflation and growth.
Atlas Newsdesk ·
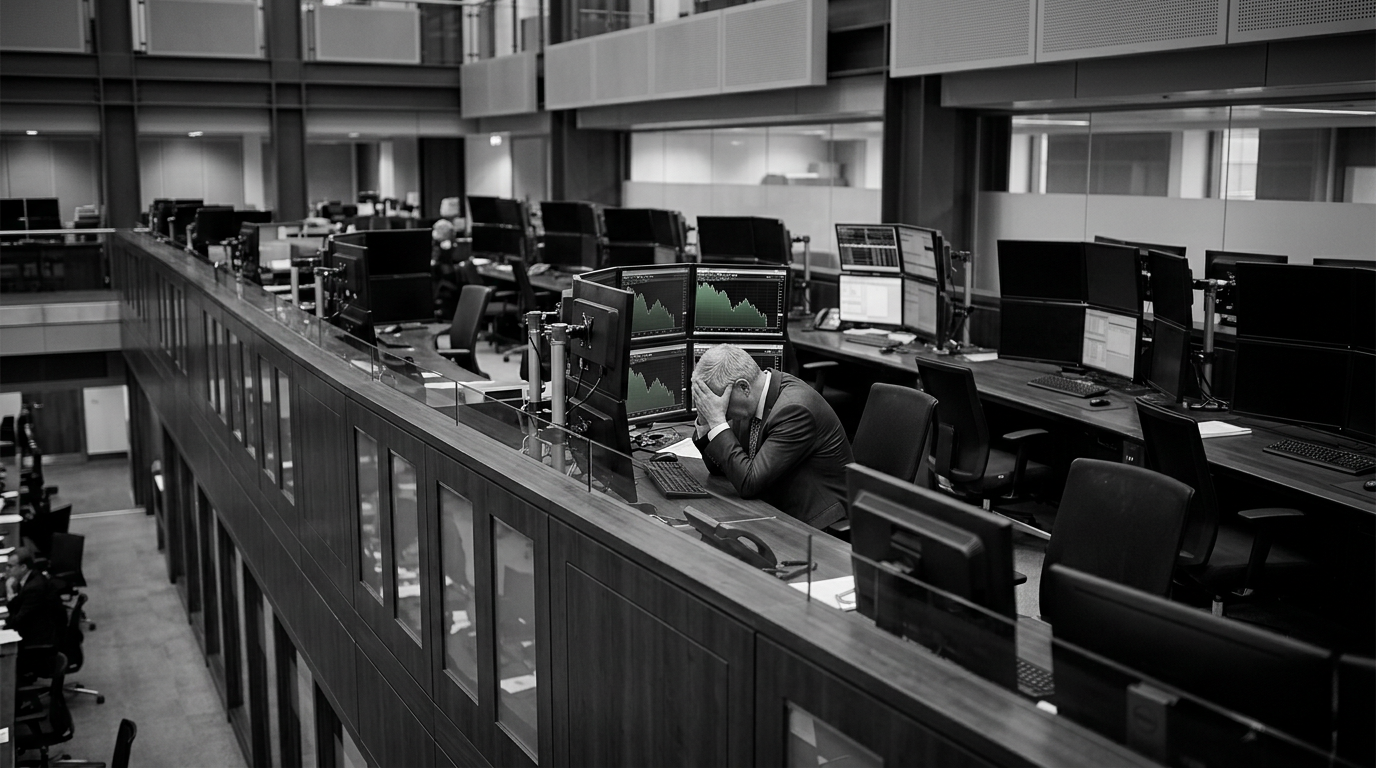
Global equity markets experienced a significant downturn on March 23, 2026 , pushing MSCI's worldwide index to its lowest point since November. This broad selloff stemmed from escalating Middle East tensions and heightened concerns over the security of global energy supplies.
The decline followed sharp losses on Wall Street on March 20 and spread across Asian markets on Monday, with major benchmarks in Seoul, Shanghai, Tokyo , and Sydney all reporting drops.
Geopolitical Risks Drive Market Shift
The immediate catalyst for the market's reaction was a rise in geopolitical risk within the Middle East. Investors began to price in the possibility of prolonged disruptions to energy flows.
According to reports, Iran issued warnings of potential retaliation against Gulf energy and water infrastructure. This threat emerged if the United States proceeded with threats to strike Iran's electricity grid.
Investor Positioning and Inflation Concerns
Global investors and major equity markets, including U.S. and Asian benchmarks, showed clear signs of a "risk-off" environment. The MSCI global gauge reached a four-month low.
Analysts indicated that the prospect of attacks on critical infrastructure raised significant concerns about the reliability of oil supplies. This fueled expectations of tougher macroeconomic conditions and prompted a more defensive stance among investors.
The escalation encouraged investors to reduce risk exposure, secure profits, and increase cash holdings. There was also a notable shift away from bonds and other assets sensitive to inflation, reflecting worries that higher energy costs could complicate both growth forecasts and price stability.
Oil's Pivotal Role in Market Sensitivity
Oil prices have already surged by over 80% this year, amplifying the market's sensitivity to any additional supply shocks. This existing volatility means that the current geopolitical conflict is being treated as a material global economic risk.
Energy acts as a crucial input cost across various sectors, including transport, manufacturing, and household budgets. Therefore, disruptions can quickly propagate through the global economy.
Uncertainties and Stagflationary Impulse
Reports flagged the risk of a "stagflationary impulse," where persistent inflation coexists with slowing economic growth. Such an environment could strain both equity and fixed income markets simultaneously.
Key uncertainties remain regarding whether the threats will materialize into actual disruptions and, if so, their duration. Markets are reacting to the perceived risk of escalation rather than confirmed damage.
For global portfolios, this episode underscores how rapidly geopolitical events can impact energy prices, which then transmit into broader asset valuations. This effect is particularly pronounced when oil prices have already seen substantial increases.
Market and Economic Implications
The market saw equities sell off as oil risks intensified, with inflation-sensitive assets facing pressure. The macroeconomic outlook includes a highlighted stagflation risk, potentially constraining policy choices for central banks.
Geopolitically, threats to Gulf infrastructure elevate global concerns regarding supply chains and energy security. For major oil-importing economies, higher crude prices could exacerbate inflation and hinder growth.
Conversely, energy exporters might see increased revenues, though heightened regional instability introduces its own uncertainties. Energy-intensive industries, such as transport and manufacturing, face higher input costs.
Financial firms and asset managers may observe a shift towards defensive allocations and increased cash holdings amidst rising market volatility. The current "risk-off" rotation suggests that further geopolitical escalation could keep cross-asset correlations high, potentially reducing diversification benefits for investors.