

S&P 500 slips as Apple, Tesla cap chip-stock rally
The S&P 500 fell 0.2% as Apple and Tesla offset a chip rebound before a heavy week of Big Tech earnings.
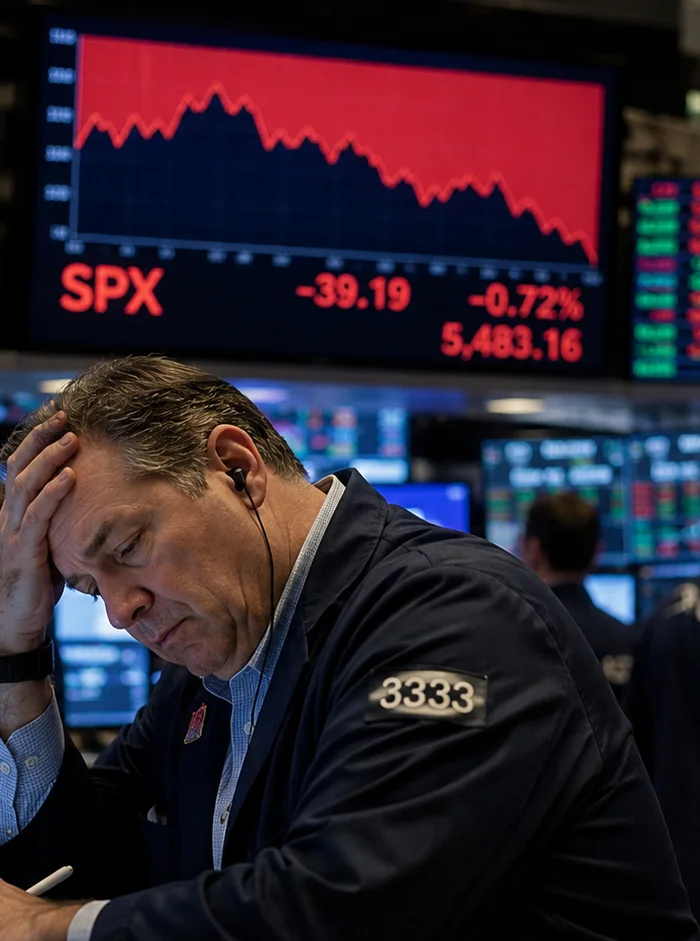
The S&P 500 fell 0.2% as Apple and Tesla offset a chip rebound before earnings from more than 80 index companies this week.
The session turned after early strength failed to hold, with the benchmark losing ground even as several artificial-intelligence-linked shares recovered. Market data showed Apple and Tesla removed more points from the index than any other constituents.
Apple’s weakness came after the iPhone maker briefly moved ahead of Nvidia on Friday as the largest listed company by market value. That rotation mattered because it showed how quickly leadership can shift inside a market still dominated by a handful of mega-cap technology names.
Apple and Tesla drag
Losses touched eight of the benchmark’s 11 sectors. Health care and materials led the decline, while technology, energy and communication services finished higher.
The Nasdaq 100 rose by less than 0.1%, a narrow gain after its weakest week in nearly a month. A basket tracking the Magnificent Seven companies was flat, showing that the market’s most influential growth stocks did not move as one group.
Tesla’s decline added pressure before its scheduled Wednesday report. For investors, the electric-vehicle maker’s update will test demand, margins and whether cost pressures are still weighing on the company’s growth story.
Chipmakers recover before reports
The Philadelphia Stock Exchange Semiconductor Index gained 0.6% after falling into bear-market territory last week. Nvidia finished up 0.2%, though it had climbed as much as 2.4% earlier in the session.
Several chip stocks did better than the broader tape. Advanced Micro Devices, Intel and Micron Technology advanced, while Sandisk rose 2.7% and Marvell Technology gained 3.3%.
The rebound reflected renewed demand for companies tied to AI infrastructure, including processors, memory, storage and networking equipment. Microsoft, Alphabet and Amazon also rose, keeping most of Big Tech positive even as the S&P 500 ended lower.
“The recent profit-taking in AI and data center-related stocks has been unwarranted, so I expect a big rebound propelled by better-than-expected earnings announcements and positive guidance,”
Louis Navellier, chief investment officer at Navellier & Associates, wrote. His view captures the central market debate: whether last week’s selling was a reset after crowded positioning or an early warning that earnings expectations have moved too far.
Earnings scenarios set the tone
The reporting calendar now becomes the main catalyst, with more than 80 S&P 500 members due to release results this week. Alphabet and Intel will give investors a direct read on how AI spending is changing revenue, capital allocation and competitive pressure across technology.
The economic calendar is light, putting more weight on company guidance than macro data in the near term. That makes management commentary on data-center demand, cloud budgets, consumer hardware and electric vehicles more important for market direction than a single backward-looking earnings number.
If Alphabet and Intel show that AI demand is translating into durable sales and constructive guidance, risk appetite could improve globally through higher equity valuations and easier financing conditions for growth companies. For Nvidia and other chipmakers, that path would support the view that data-center spending remains a multi-company revenue engine; for the wider semiconductor industry, it would favor continued investment in memory, networking and advanced processors.
If guidance instead points to slower AI monetization, tighter customer budgets or margin pressure, the effect would move in the opposite direction. Global markets would likely price a lower tolerance for long-duration growth assets, Apple and Tesla could face sharper scrutiny over their own demand signals, and chip suppliers would have to defend valuations built on heavy infrastructure spending.
A third path is narrower: strong chip results but weak breadth in the rest of the index. In that case, the S&P 500 could remain dependent on a small group of technology leaders, leaving health care, materials and other cyclical sectors as the test of whether the rally can widen beyond AI.
The open questions are concrete. Investors need to see whether Tesla’s update stabilizes sentiment, whether Apple’s pullback is company-specific or part of a broader mega-cap rotation, and whether semiconductor gains can survive a week packed with earnings rather than just a one-day rebound.
More stories
- AI trade steadies as Nasdaq futures climb after tech rout
- Gold prices retreat as markets await key US labor statistics
- Brent crude rebounds as chip shares extend their retreat
- French MPs reject 2027 budget revenue plan 458-0
- AI stocks split as Democrats win Congress and tech gains
- US Treasury expands Iran sanctions on maritime operators
- Trump expands Canada tariffs with 1930 trade law next month
- SpaceX stock faces 1.37 billion share unlock in August
- Kalshi faces New York sports-event gambling ruling test
- Kenya economy faces weakest growth since Covid-era shock
Latest news
- AI bots disrupt university libraries with 11,000-search surge
- OpenAI and Anthropic face AI spend slowdown to 1.5%
- Poland starts 2 days of mourning over 6 Krakow deaths
- Home Office faces suit over almost 1,500 EU residency cases
- Kalshi faces state gambling laws after two appeals losses
- Uganda ties construction push to $500bn economy target
- MaxxBench exposes 23-point coding-agent gap in revised tests
- Armenia faces EU democracy test over opposition cases