Press release claims China chip packaging growth; what OEMs and software vendors should expect
China’s semiconductor packaging market is set for growth via AI and 5G. Treat these claims as marketing; verify capex and hiring before shifting strategy.
Hannah Vogel ·
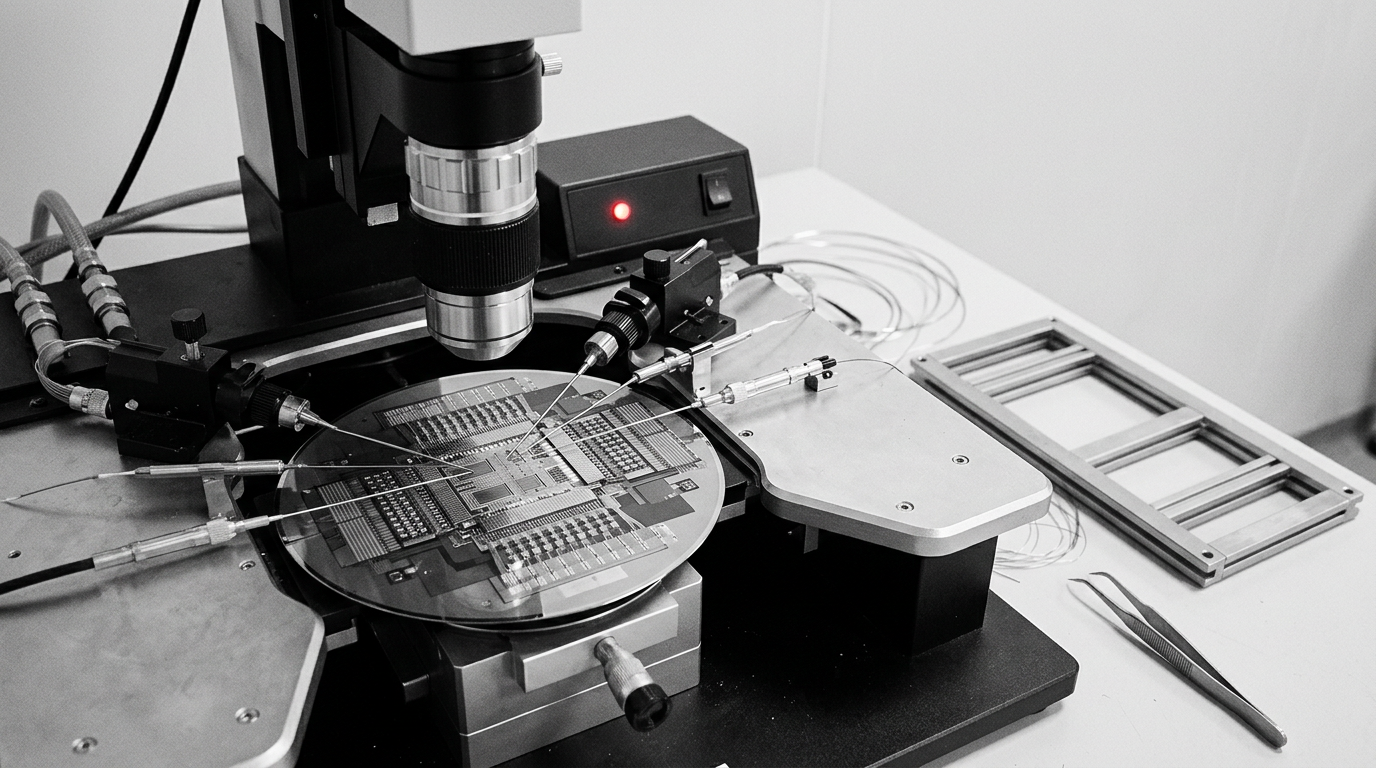
In a GlobeNewswire press release dated September 14, 2026, the issuer claims China’s advanced semiconductor packaging market is “poised for growth” as AI, 5G and chip self‑reliance stimulate “new investment opportunities.” It is a press‑release wire item, not an audited filing or regulator disclosure, and should be treated as self‑reported marketing until corroborated by capital‑spending or capacity data. For operators, the practical question is what—if anything—changes in procurement timelines, software licensing, equipment sales cycles and supplier risk this quarter, not in a brochure’s forecast year. GlobeNewswire
This is marketing, not a filing; the denominators and time horizon are unstated
The headline asserts a growth posture but does not specify a baseline, period, unit of measure, or the segment boundaries that matter to buyers—whether the claim concerns revenue, capacity, unit output, or mix shift within advanced packaging categories. Without those denominators, the claim is not decision‑grade for procurement or sales planning. Press‑release language also tends to collapse distinct dynamics—policy support for “self‑reliance,” end‑demand from AI and 5G, and supplier localization—into a single vector, obscuring which mechanism would actually drive purchase orders in the next two to three quarters. Until an OSAT, foundry or materials vendor publishes capex guidance, a facility ramp, or booked‑orders detail, the “poised for growth” line reads as a lead‑generation hook rather than an investable or operational signal. [GlobeNewswire]
If packaging spend ramps, the first place it lands is software seats and factory systems
For enterprise software sellers, a genuine expansion in advanced packaging capacity usually shows up as higher demand for design and verification tool seats, factory MES, scheduling and yield‑management systems long before a full equipment refresh is visible. The decision for buyers is not whether to embrace “growth,” but whether to procure additional licenses under term or move marginal workloads to consumption to match uncertain ramp timing. Vendors that still price strictly by seat will find themselves renegotiating to hybrid models if customers prefer to carry variable cost during pilot and early ramp phases. Procurement will also insist on data‑use and confidentiality terms suited to packaging flows that embed proprietary chiplet and interconnect IP—legal gets a vote before any tool is switched on. [GlobeNewswire]
Equipment sellers should budget for longer qualification cycles and local content tests
Even if investment intent exists, advanced packaging lines require multi‑month qualification on materials stacks, reliability and throughput. Policy rhetoric about local supply chains often translates into explicit local‑content targets in purchase agreements. That elongates the sales cycle: more vendors to qualify, parallel material trials, and additional factory acceptance tests. Sellers should expect a bigger share of deal value to be gated by on‑site performance milestones rather than upfront bookings. If the growth is real, watch for clusters of installation and service job postings near planned sites and an uptick in spares and consumables orders that precede full tool shipments. [GlobeNewswire]
“Self‑reliance” claims collide with procurement governance and dual‑sourcing rules
For device makers and fabless design houses buying advanced packaging as a service, board‑approved procurement policies still require dual sourcing, audit rights and continuity plans. A pivot to domestic providers will be tested against yield history, IP protection, and export‑compliance posture on any imported subassemblies. Expect more contracts to include staged volume commitments with price‑protection clauses, rather than single‑provider lock‑ins justified by policy slogans. Sellers leaning on “self‑reliance” messaging will still need to pass vendor‑risk scoring and offer SLAs that map to customers’ own downstream obligations. [GlobeNewswire]
Sales and marketing will need to shift from macro narratives to factory math
For go‑to‑market teams, the operative move is to retire the macro‑geopolitics slide as the lead and anchor the conversation in takt time, die stacking yields and cycle‑time improvements that matter to a line manager. Buyers will ask whether the claimed improvements in advanced packaging translate into fewer rework passes and higher known‑good‑die availability in volume. Pricing that assumes smooth utilization from day one will encounter pushback; a ramp‑indexed price curve—more expensive at low utilization, trending down as throughput and yield stabilize—better matches buyer risk and reduces discounting at quarter‑end. The more sellers rely on generalized growth language, the more procurement will demand pilot‑line proofs before committing cash. [GlobeNewswire]
For software procurement, hybrid licensing will be the default during any ramp
If capacity adds materialize, packaging‑aware EDA and factory software footprint will grow, but procurement will resist expanding perpetual seats until sustained utilization is visible. Expect more short‑term term licenses, burstable consumption blocks, and tighter true‑up provisions. Legal will scrutinize data residency and isolation for multi‑tenant analytics tools that handle yield and defect data considered sensitive. Vendors able to ring‑fence customer data and support on‑prem, air‑gapped deployments will shorten deal cycles; those who can only offer shared‑cloud analytics will face longer security assessments and potential carve‑outs. [GlobeNewswire]
What would count as evidence in the next two quarters
Because the source is a press release rather than a filing, the near‑term corroborators are operational not rhetorical. If the market is truly “poised for growth,” we should see: public capex or capacity announcements by major packaging providers or their suppliers; an increase in factory‑operations and equipment‑service hiring in relevant regions; and clearer guidance from software vendors that China packaging demand is lifting their booked or billed revenues, even if reported as non‑GAAP operating metrics. Absent these, a reasonable read is that the press‑release claim is aimed at investors and lead funnels rather than near‑term purchase orders. [GlobeNewswire]
The skeptic’s read: AI demand may be real while packaging mix stays constrained
A fair counter is that even with AI and 5G tailwinds, the tightest constraints may sit in materials availability, tool lead times, or specialized talent rather than capital budgets. In that scenario, “poised for growth” masks a slower mix shift within packaging—notably more complex assemblies captured in a narrow set of facilities—leaving broader supplier lists unchanged this fiscal year. That would explain a year of strong plant tours and pilot lines but muted recognized revenue for toolmakers and software vendors. The only way to distinguish narrative from reality is to track purchase‑order conversion and sustained utilization, not announcements. [GlobeNewswire]
The bottom line for operators is to separate tiered evidence: a press‑release wire is the lowest‑assurance tier. Until there are filed capex plans, audited capacity disclosures or at minimum specific booked‑order figures from counterparties, keep macro‑narratives in the investor‑relations deck and manage your pricing, procurement and staffing to observed factory math.