

CoreWeave bond yields hit 15% as AI funding doubts deepen
CoreWeave’s junk bond yields reached 15%, with investors questioning how much additional debt the AI computing provider might raise.
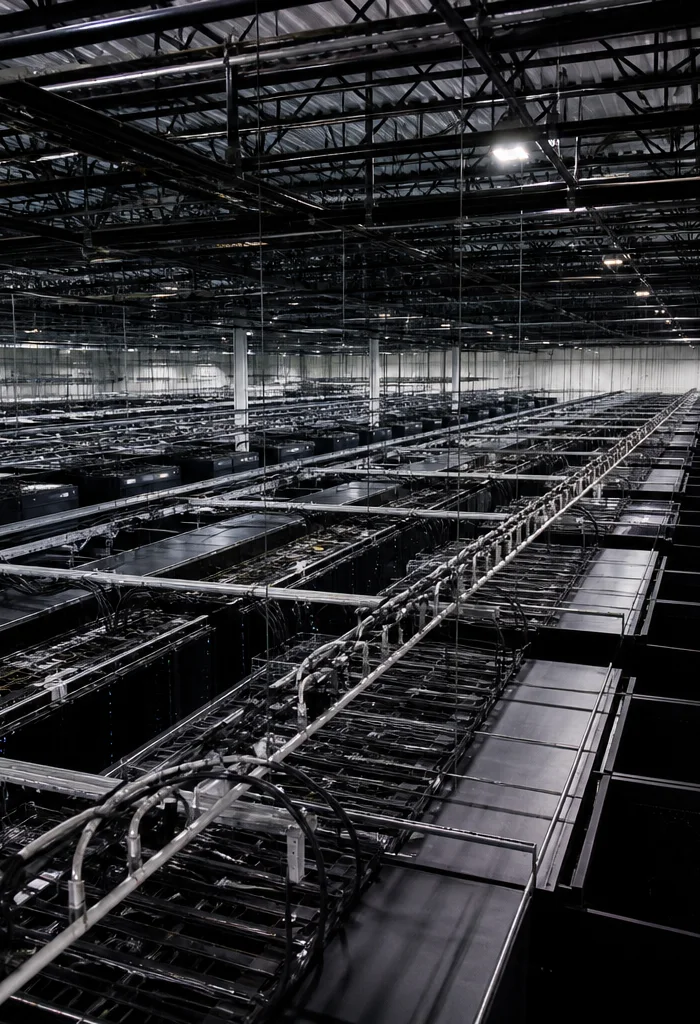
CoreWeave’s junk bond yields reached yüzde 15, with investors questioning how much additional debt the AI computing provider might raise.
The increase followed comments from a company co-founder about pursuing investment-grade financing, where insurers represent a potential source of capital. Lenders interpreted those remarks as a possible indication of heavier borrowing, rather than simply a change in where the company obtains funding.
CoreWeave said its financial position “more than supports” its debt obligations. That assurance addresses its capacity to meet payments; the concern expressed by investors also encompasses the volume of debt that borrowers may bring to market.
CoreWeave explores another financing channel
The distinction between those concerns matters for understanding the financing debate. A borrower’s ability to service existing obligations and investors’ willingness to absorb additional securities are separate questions, even when both influence discussions about its financial health.
CoreWeave operates data centers and supplies AI computing services, placing its financing needs within the broader expansion of artificial intelligence infrastructure. Its interest in the investment-grade market introduces another potential funding channel alongside the speculative-grade bonds now attracting scrutiny.
The co-founder’s comments described an avenue under consideration, not a completed financing. They did not establish how much the company would borrow, when it would issue debt or what terms investors would receive, leaving the scale of any additional financing unresolved.
Debt supply divides investor assessments
John Yovanovic, co-head of leveraged finance at MetLife Investment Management, identified prospective issuance as the central issue. “The problem is not that credit profiles have changed in the last year, it’s that we’ve got another year and a half of supply coming,” he said.
His assessment shifts attention from a single borrower’s current finances to the amount of financing investors may be asked to provide. It is an investor’s judgment about future supply, not a confirmed schedule of debt sales or proof that CoreWeave’s creditworthiness has deteriorated.
Nvidia Corp. Chief Executive Officer Jensen Huang also defended CoreWeave’s financial standing. Nvidia is both an investor in CoreWeave and a supplier to the company, which is a major customer, giving the chipmaker a commercial and financial interest in the discussion.
Borrowing terms remain the unresolved test
If CoreWeave secures investment-grade financing, the terms would help establish whether that channel broadens its funding options without intensifying existing lenders’ concerns. Access alone would not answer the question investors have raised about the total amount of borrowing.
If prospective issuance instead meets limited investor demand, CoreWeave and other AI borrowers could face pressure to offer more attractive terms or reconsider financing plans. Any wider effect on infrastructure investment would depend on whether those funding constraints changed companies’ spending decisions; the available information does not establish such a change.
The next concrete test is whether CoreWeave turns its exploration into a financing proposal with a disclosed size and structure. Those details would allow investors to assess the additional obligations rather than infer them from management’s comments.
More stories
- DeepSeek updates AI model as speed and cost rivalry grows
- The Week in Games: Selective capital meets harder scoreboards
- Bhaag Neha Bhaag draws 2,700 players in CJP protest game wave
- Japan & Asia: Switch 2 leads Famitsu chart with 22,420 units
- Kotukh maps quantum side-channel edge to AES-128 rank 2^58.6
- LLM crisis reports capture 5.4%-11.0% of official figures
- EU AI Act model rules hand Brussels new powers from today
- DeepSeek-V4-Flash Challenges GPT-5.6 Luna on Price
Latest news
- Wall squats may lower blood pressure after four weeks
- 8-hour eating windows beat controls by 5 pounds in TRE trials
- Researchers link diabetic ulcers to stalled immune repair
- Loneliness and isolation linked to 5.8 fewer healthy years
- Weiss warns of breast cancer care gap after treatment
- CoreWeave gains ARK backing as borrowing concerns persist
- Egypt offers Saudi defense help, seeks parliament's role
- Bangladesh measles outbreak claims 1,147 lives, WHO says