Revolut wins French banking license for euro expansion
Revolut wins a full French banking license, adding a euro-area base after its March 2026 UK license and widening scope for deposits and lending.
Claire Dubois ·
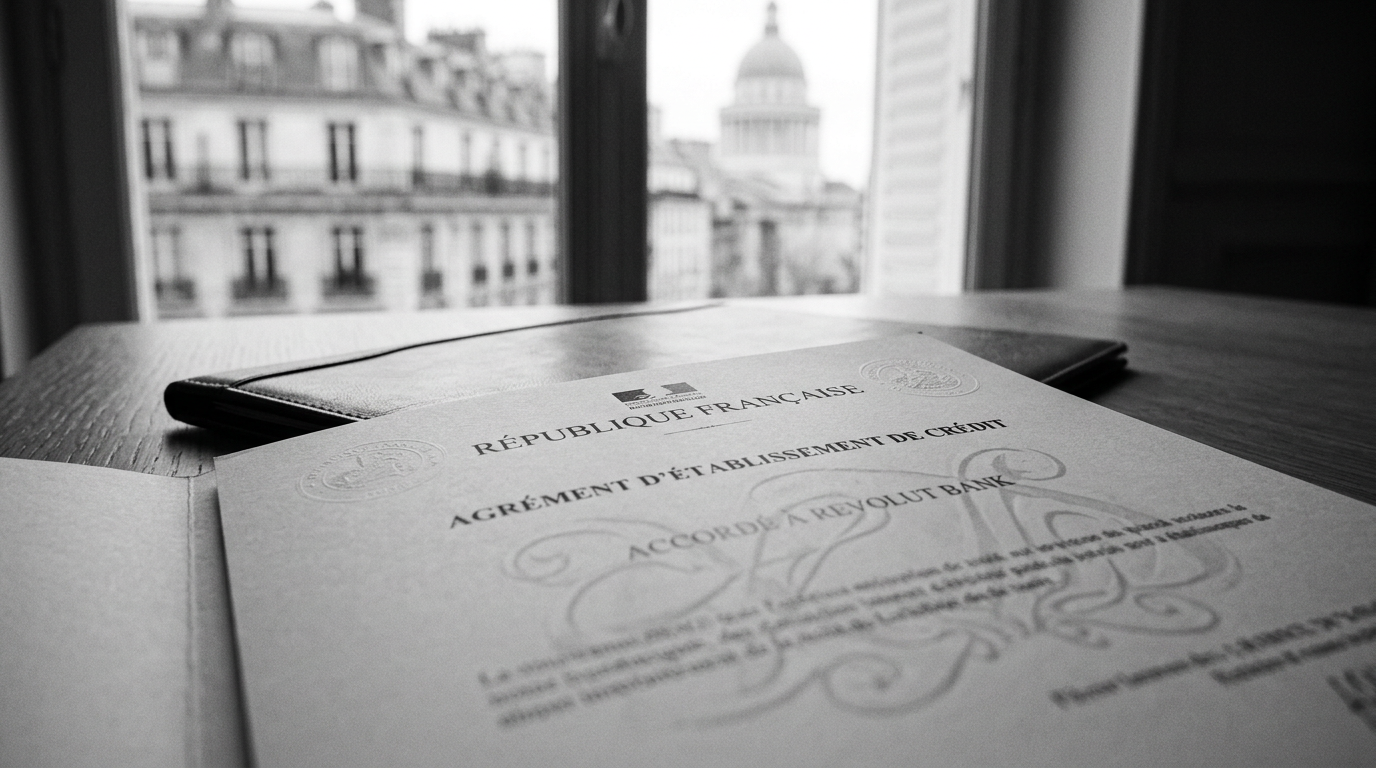
Revolut has obtained a full banking license in France, adding a major regulatory foothold as the fintech pushes deeper into the euro area. The approval strengthens Revolut’s position as it markets itself as a cross-border retail banking challenger, building on the UK banking license it received in March 2026.
The French authorization matters because a full banking license typically allows a broader set of activities than an e-money license, particularly in deposit-taking and lending. That wider permission set can enable a firm to expand product breadth and alter how it funds growth, compared with models more reliant on payments and e-money features.
How euro-area supervision and licensing intersect
In the euro area, the European Central Bank (ECB) oversees significant institutions via its Single Supervisory Mechanism. At the same time, national authorities remain central to licensing decisions and to day-to-day oversight, depending on a firm’s size and structure.
For France specifically, the supervisory perimeter and the legal framework around a full banking license can shape what services are offered locally and how quickly they can be rolled out. That makes the French license a potential operational pivot for Revolut’s euro-area strategy, alongside its earlier UK authorization.
The macro backdrop for lenders remains ECB-driven
The operating environment for all lenders in the euro area remains heavily influenced by the ECB’s monetary-policy stance, set primarily through its policy rates. Policy rates affect funding costs, credit demand, and the repricing of deposits and loans, which in turn influences how banks and licensed challengers compete for customers.
Investors and policymakers frequently track inflation through the Harmonised Index of Consumer Prices (HICP), the euro area’s standard gauge that feeds into ECB decision-making. Even with a new entrant gaining permissions, sector dynamics still sit within this broader macro framework that determines the baseline cost of money.
Competitive pressure in a French market led by universal banks A full French banking license could increase competitive intensity in a market where large universal banks dominate distribution and maintain pricing power, particularly in everyday retail products such as payments, deposits, and consumer credit. The immediate mechanism for incumbents is margin pressure if a fast-growing challenger can broaden its product set and price aggressively.
Established banks may be pushed to respond through higher deposit rates, lower fees, or improved digital features. The market implication described by analysts is less about a single, direct rates reaction and more about a gradual shift in how competition influences bank funding and profitability over time.
Funding mix, bank spreads, and stress-era tools in the background If more fintechs move from e-money models toward full banking licenses, they could rely more on deposits and regulated balance-sheet lending. That shift could change the funding mix across the sector and become a theme analysts monitor in bank performance and bank bond spreads.
Over a longer horizon, analysts will also watch whether competition affects banks’ appetite for sovereign debt holdings and wholesale funding. In stress episodes, the sensitivity of Italy’s BTP–Germany’s bund spread to financial-sector headlines is one channel that could draw attention.
Separately, the ECB retains crisis-era tools aimed at preventing destabilizing market dynamics, including the Transmission Protection Instrument (TPI) and Outright Monetary Transactions (OMT). These are designed as safeguards against unwarranted and disorderly market moves that threaten monetary-policy transmission, and they remain part of the institutional backdrop as competitive dynamics evolve.
A dated checkpoint for rollout in France
By 2026-11-10, a key test set out by analysts is whether Revolut materially increases its customer acquisition pace in France and launches a broader local product suite using the new permissions, including more lending and deposit features. Rapid expansion would be evidenced through accelerated product launches and sustained user growth that triggers measurable reactions from French incumbents in pricing or features, while slow uptake would point to a strategically important license that does not quickly reshape the market.