IMF says Bank of Japan has room to normalize rates further
The Bank of Japan has IMF support to keep normalizing policy as inflation stays above target and yen pressure keeps currency policy in focus.
Lauren Collins ·
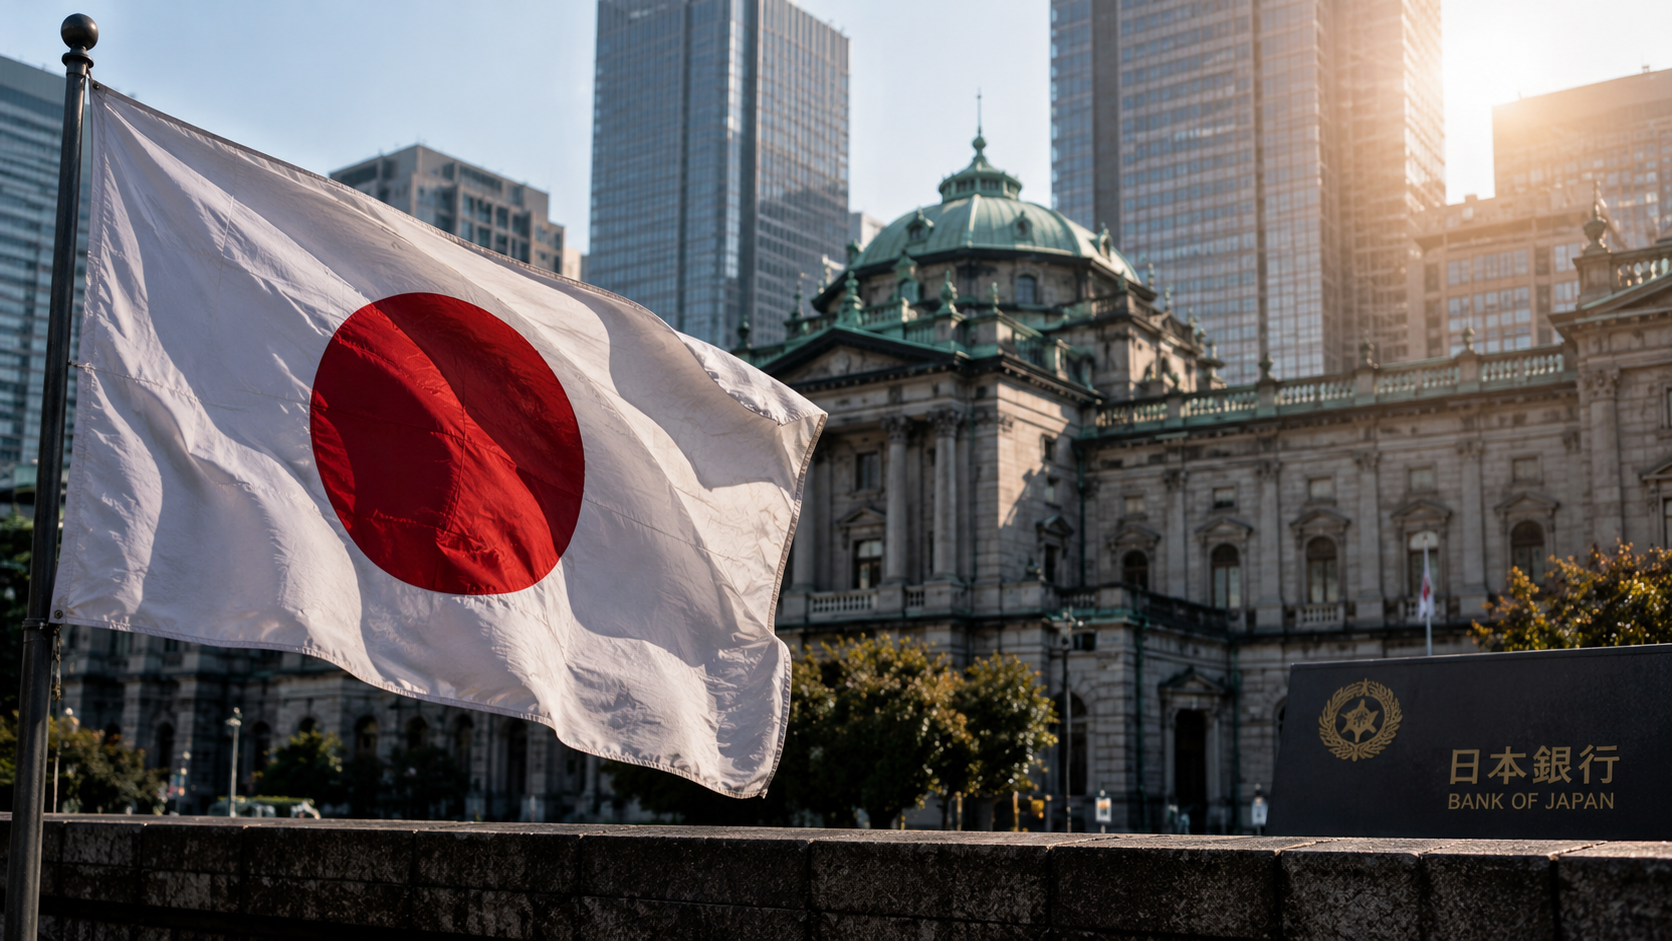
The Bank of Japan has IMF support to keep normalizing policy as inflation stays above target and yen pressure keeps currency policy in focus.
Dan Katz, the International Monetary Fund’s first deputy managing director, said Japan is in a long transition away from the ultra-low-rate framework that shaped its economy for almost three decades. His comments put the central bank’s next moves inside a broader political economy shift: higher prices, a weaker yen and reforms that are altering who benefits from Japanese policy.
Katz backs further normalization
Katz said Japan is undergoing a "very significant long-term transformation," tying the change to structural reforms begun under former Prime Minister Shinzo Abe. Those reforms, he said in a televised interview from Cape Town on Thursday, are only now producing visible results.
The Bank of Japan has already begun exiting the low-rate regime that defined much of Japan’s post-bubble era. Katz said he expected the central bank to act as needed to meet its mandate, which he described as delivering on inflation while supporting growth.
"Inflation is still modestly above target, so I would expect a continued normalization," Katz said when asked what the BOJ should do to help the Japanese currency. The phrasing matters: it supports more policy adjustment, but leaves the timing and size of any move with the central bank.
Yen intervention narrows choices
The currency issue has already pulled Washington into the market. The US last week joined Japan in the first joint intervention in the yen in 15 years, with US Treasury Secretary Scott Bessent warning traders that further action remained available if officials judged it necessary.
Bessent wrote in an Aug. 4 post on X that intervention alone would not solve what he called the yen’s "substantial undervaluation." That places monetary policy, market operations and official messaging in the same frame, without making any one of them a complete answer.
The yen has weakened about 1.3% from its Aug. 3 high and traded near 158.18 per dollar at 3:17 p.m. in London, according to the source figures. A softer currency helps some exporters when overseas earnings are translated back into yen, but it raises costs for households and firms exposed to imported food, fuel and materials.
That distributional divide is central to the policy problem. Banks, savers and insurers can gain from a more normal rate structure, while highly indebted borrowers and companies reliant on cheap funding face a tighter financing environment.
AI investment supports resilience
Katz also described the global economy as more resilient than many observers expected, despite geopolitical tensions and disruptions to supply chains. He pointed to technological change, especially artificial intelligence, as a source of investment and demand that is helping support growth.
His remarks came during his first visit to Africa as an IMF official after joining the fund last year. Before that, Katz served as chief of staff at the US Treasury, a role that placed him near the policy coordination now visible in the yen response.
He also cited financial innovation in Africa, including mobile money, as an example of new technologies creating value for consumers and businesses. That observation links Japan’s normalization debate to a wider global pattern: economies are trying to lift productivity while managing the inflation and currency effects of policy shifts.
If Japanese inflation remains above target, continued normalization would tighten financial conditions at the margin, support the Bank of Japan’s credibility and push banks and asset managers to reprice yen risk. For the global economy, that path would test whether growth can absorb higher Japanese rates after years in which cheap yen funding was a fixture of cross-border markets.
If inflation eases instead, the BOJ would have more room to slow the process, reducing pressure on borrowers while leaving the yen more exposed to interest-rate gaps with other major economies. The main open question is whether currency intervention, rate expectations and domestic price data can align long enough to move the yen without undermining growth.