Two jobs, $75,000 in student debt: How one Florida woman works to get by
A Florida woman works two jobs to manage $75,000 in student loan debt, reflecting a broader rise in US household debt to $18.8 trillion.
Ayla Demirhan ·
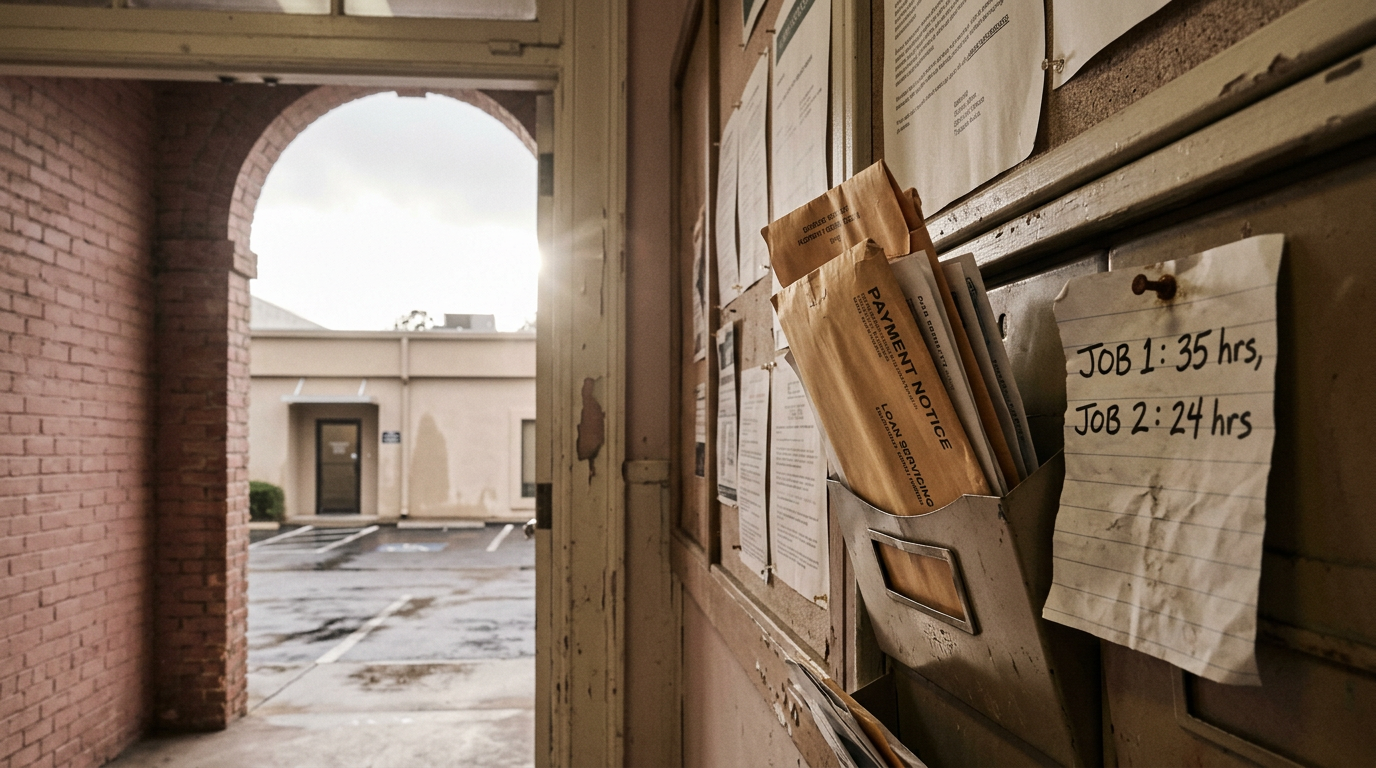
A Florida resident, Rachel Jordan, is managing approximately $75,000 in student loan debt by working two jobs, totaling around 70 hours weekly. Her strategy, which began in 2025, aims to aggressively reduce her financial obligations. This personal effort reflects a broader national trend of increasing household debt across the United States.
Jordan's employment includes a role in commercial real estate loan servicing and a second position at a retail store in Tampa, Florida. Her financial plan involves making monthly payments of $1,600 to $2,000 towards her student loans, even while they remain in forbearance. This approach is part of a larger strategy that previously saw her eliminate credit card debt last year.
Personal Debt Management Strategies
Her long-term financial aspirations include accumulating $100,000 in retirement and high-yield savings accounts. The student loan debt originated from two undergraduate degrees in accounting. In 2022, Jordan applied for student loan forgiveness for one of these degrees and is currently awaiting a determination, with her loans remaining in a state of forbearance.
Broader Economic Context of US Debt
The persistence of student loan debt, even with federal programs like forbearance and forgiveness applications, highlights structural issues within the higher education financing system. Many borrowers, like Jordan, are compelled to adopt rigorous personal finance strategies to navigate these obligations. The economic implications of such widespread debt include potential constraints on consumer spending and long-term wealth accumulation for a significant portion of the population.
Implications for Consumer Spending
Implications
Country Impact: The rising U.S. household debt, exemplified by individual struggles with student loans, indicates potential headwinds for national economic growth. High debt levels can suppress consumer spending and investment, impacting overall economic vitality.
Industry Impact: The financial services sector, particularly student loan servicers and credit card companies, faces ongoing challenges and opportunities related to debt management. Retail and real estate sectors may experience fluctuating demand due to constrained consumer finances.
Market Impact: Financial markets may reflect concerns over consumer debt, potentially influencing interest rate policies and investment in consumer-facing industries. The burden of student loans could also affect long-term capital formation and retirement savings trends.