Robot IPOs in China face checks after Unitree stock slide
China is slowing some robot IPOs after Unitree’s volatile debut, as regulators examine valuations and state-linked revenue.
Jason Kwon ·
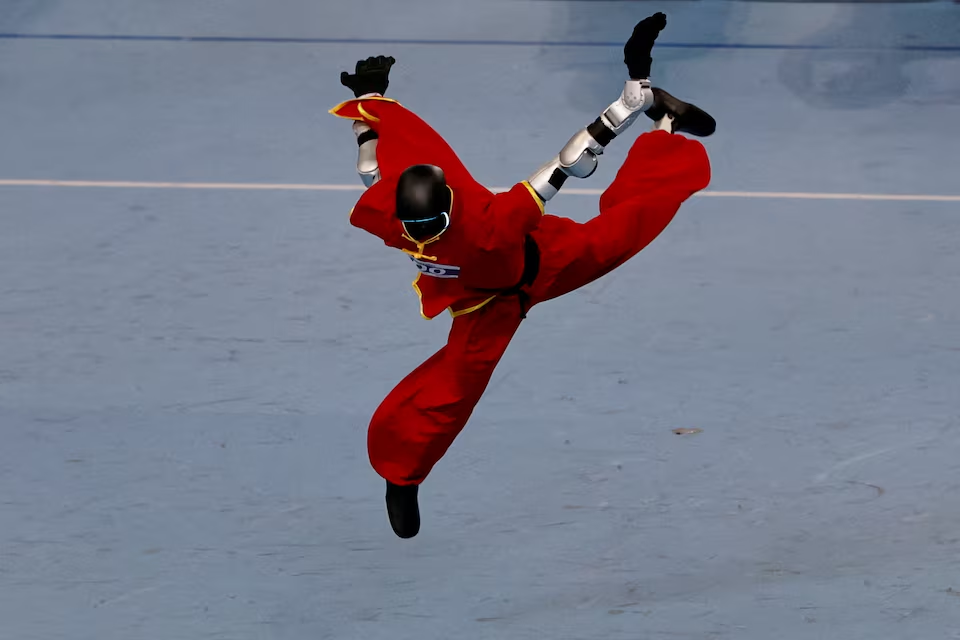
Robot IPOs in China are slowing after Unitree’s volatile debut. Regulators are testing whether state-linked sales support private demand.
The pause is being applied through informal window guidance rather than a published ban, according to people briefed on the discussions. One person said humanoid listings had effectively stopped for now; another described the action as a sector slowdown.
Unitree’s 55% retreat
Unitree Robotics (688836.SS), a maker of humanoid and quadruped robots, climbed more than fivefold in its Shanghai debut a month ago. Its shares have since fallen 55% from their peak, giving regulators a public marker for how quickly the trade can reverse.
The China Securities Regulatory Commission is examining whether valuations in the humanoid robot sector are being supported by commercial orders or by government-linked projects, the people said. The distinction matters for listing reviews, where revenue quality can affect whether a company is seen as ready for public investors.
State-backed revenue faces review
Beijing has promoted embodied intelligence, the term used for AI systems that can sense and act in the physical world, as a strategic emerging industry. That policy support has drawn money from private investors and local governments into companies building robots, training systems and related hardware.
Leo Wang, a venture capitalist at Qianchuang Capital, called the robotics investment wave “campaign-style innovation,” a Chinese phrase used for capital moving quickly into sectors favored by policy. He said enthusiasm around embodied AI had exceeded earlier internet and new-energy cycles, with industrial robot makers shifting toward humanoids and startups attracting investors within weeks.
Wang said some founders were declining conventional due diligence as demand for private deals rose. He also said some private-market projects had already taken valuation cuts of 30% to 50%, a range that shows how quickly pricing can change when funding conditions tighten.
Regulators are giving particular attention to revenue from robot data collection centers and joint ventures backed by local governments, according to a person close to humanoid robot investors. In some arrangements, local authorities could provide 80% to 90% of initial investment, the person said.
Those projects can create orders that lift reported sales and help companies approach listing thresholds. The regulatory question is whether that revenue would remain if buyers were independent customers paying for factory deployment, logistics work or other recurring commercial uses.
Revenue claims meet market tests
The same person estimated that valuations at some robot companies could fall 60% to 70% if data collection center revenue were excluded. That estimate is one investor’s view, but it captures the pressure on companies whose sales depend on arrangements linked to policy support.
Shao Tianlan, CEO of Mech-Mind Robotics (9615.HK), alleged in a WeChat post this month that some highly valued embodied AI firms were recording sales through data collection centers, related-party deals and other arrangements he described as unsustainable. Mech-Mind shares have fallen nearly 20% from their debut-day high on September 1.
At least half a dozen Chinese humanoid robotics firms are preparing to list, including Deep Robotics, X Square Robot and AGIBOT. Their plans now sit inside a review environment focused less on technical demonstrations and more on deployed products, order volumes and customer independence.
Mainland Chinese fundraising has otherwise been improving, which makes the robotics caution more targeted than market-wide. Companies have raised $148.9 billion through share sales and convertible offerings so far in 2026, up 59% from the same period a year earlier, with technology companies accounting for 41% of the total, according to LSEG data.
Three paths for robot listings
If the slowdown holds, the immediate effect would be tighter access to public capital for robot startups and a more selective pipeline for bankers and funds. For Unitree, continued scrutiny would keep attention on post-listing trading and order quality; for the sector, it would push companies to prove factory and service use cases before valuation premiums return.
If regulators instead allow filings to proceed for companies with clearer independent demand, China’s robotics industry could move from policy-driven financing toward a narrower set of commercially tested issuers. That path would support technology fundraising without adding as much speculative pressure to broader equity markets.
If revenue quality concerns widen, valuation resets in private robotics deals could affect venture funds, local-government investment vehicles and suppliers tied to humanoid projects. The main open question is whether companies can convert state-supported pilots into repeat orders from customers that are not financing the sector as an industrial policy goal.