Automakers and builders face procurement shifts as vendors tout high‑strength steel growth
The high-strength steel market is set to grow through 2033. Procurement teams must adjust strategies now to avoid supply risks and rising costs.
Hannah Vogel ·
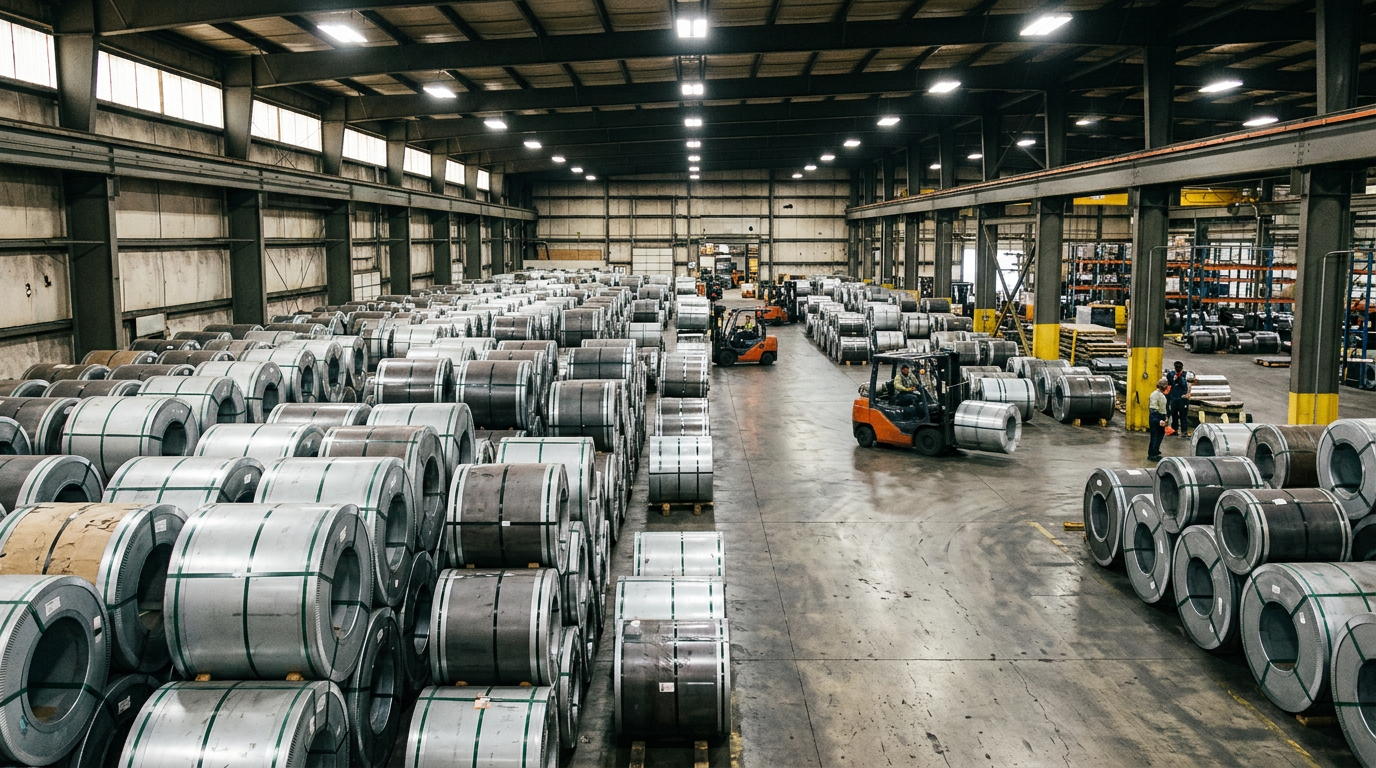
In a press release distributed via GlobeNewswire on 22 September, an unnamed issuer claimed the high‑strength steel market is “poised for robust growth through 2033,” citing rising automotive and EV lightweighting, infrastructure renewal, advanced steelmaking, recyclability and seismic resilience as the main demand drivers. This is a single‑source, company‑issued item and is not independently verified; the release does not present audited comparatives, and it does not disclose the baseline year, region coverage, price assumptions or grade definitions underpinning its growth claim. That makes the claims marketing, not finding, and operators should treat them as such until suppliers publish filed data or disclosed contracts that substantiate the trajectory. [S1]
The release claims growth but omits the denominator operators need
The headline asserts growth through 2033 but does not state from what base, at what pace or where. Without a disclosed methodology, it is unclear whether the claim covers advanced high‑strength steel (AHSS) only or also ultra‑high‑strength (UHSS), whether stainless and maraging grades are included, or whether the forecast is volume, value or both. The press item also does not state whether the growth rate assumes steady energy and raw‑material inputs or bakes in future price surcharges and decarbonisation premiums. For buyers, those omissions matter: the procurement levers differ if volumes rise on flat prices versus if value growth is merely a function of higher surcharges. Until those baselines are transparent, the “robust growth” framing is unaudited and should be considered a vendor narrative rather than a market fact. [S1]
Lightweighting’s promise becomes a contracting problem long before it becomes a cost saving
Automotive and EV teams chasing weight reduction trend toward higher‑strength grades to hit crash, range and efficiency targets. If the release’s demand arc holds, the practical change is commercial, not just technical: procurement has to lock in supply for particular chemistries and form factors, manage longer qualification cycles, and negotiate weldability and forming guarantees that reduce downstream scrap. The press item’s own emphasis on lightweighting implies a shift in where dollars move — toward higher‑spec coils and sheets that carry process risk if stampers lack experience with springback and edge cracking at higher strengths. That means a buyer’s “savings” on vehicle mass can be offset by higher rework unless contracts explicitly address yields, surface finish tolerances and tooling support from mills or service centres. None of those risks are priced in by a headline forecast; they show up in the buyer’s variable cost line if unaddressed. [S1]
Infrastructure renewal shifts demand timing and compliance risk to the bidder
The release points to infrastructure renewal and seismic resilience as growth vectors. Translating that into procurement mechanics: contractors bidding bridges, rails or public buildings will see specifications that reference higher minimum yield strengths and ductility requirements. In turnkey bids, the risk of meeting those specs sits with the bidder unless supply contracts back‑to‑back the obligations with mills and processors. If market demand tightens for these grades, bidders without pre‑negotiated allocations could face lead time exposure or be forced into spot purchases at a premium — a risk not captured by a generic “robust growth” forecast. Compliance adds another layer: in many public tenders, traceability and recyclability claims must be documented down to heat numbers. The press item invokes recyclability as a driver but does not name what standards or assurance levels its issuers assume, leaving buyers guessing about what documentation burden to plan for. [S1]
The channel will matter more than the mill if service centres control allocation
Even if mills increase capacity for high‑strength products, many downstream buyers source through service centres that slit, blank and warehouse coil. In practical terms, this means the effective constraint — and the price — can sit in the distribution layer when demand spikes. The press release has nothing to say about where in the channel the supposed growth concentrates, or how allocation decisions will be made in tight quarters. For operators, that is a subtle but critical omission: a mill framework agreement without a corresponding service‑centre slot does not guarantee delivery. Buyers should test allocation language, consignment availability and surcharge pass‑through terms with both mills and intermediaries, rather than assume the channel will absorb a demand surge without repricing or re‑prioritising customers. [S1]
The skeptical read: substitution and process constraints can cap adoption even in the face of headline demand
No one in the release packet is on the record addressing the obvious counter‑case: in some applications, aluminium, composites or casting strategies provide alternative paths to weight reduction or seismic performance, reducing reliance on high‑strength steel. Process realities can also slow uptake. Higher strength often narrows the forming window, raising scrap rates and requiring re‑engineered dies and fixtures; in construction, welding procedures and inspector qualifications need updates before structural uses can scale. None of this refutes the press item’s directional claim, but it does mean that a demand forecast predicated on universal substitution can overstate actual consumption if buyers choose different materials or defer deployments awaiting capex, training or code acceptance. Without published assumptions, the press release cannot be tested against those constraints. [S1]
What changes for buyers if the forecast proves directionally right
Treating the claim as a scenario rather than a certainty, automotive and infrastructure buyers should expect commercial terms to evolve: longer qualification lead times baked into master supply agreements, tighter clauses on forming and weldability support, and explicit surcharge schedules tied to higher‑value grades. Procurement organisations may need to re‑sequence budget approvals, moving more cost into variable lines based on consumption rather than fixed seat‑like allocations — a shift that changes how plant managers and CFOs view usage and waste. On the sales side, mills and processors that can guarantee formability support and rapid trial coils will gain share over those selling product without process integration. In parallel, distributors with flexible inventory slots for advanced grades will likely command better margins than those tied to commodity coils. None of this relies on the press release being “true”; it simply follows from the buying behaviour required to de‑risk high‑strength deployments once engineering teams commit to those specs. [S1]
The line to hold: treat this as marketing until the numbers show up in filings or contracts
Because the press item is unaudited and does not disclose its methods, the defendable course for operators is to insist on evidence in bid documents and supplier negotiations. For automakers, that could mean requiring mills to tie forecasted availability to named production lines and to provide conversion support in writing; for builders, it could mean aligning bid schedules with verified allocation letters and setting clear conditions for surcharge pass‑through. If suppliers believe demand will rise, they will accept some of those commitments; if they resist, that is itself a signal about the firmness of the forecast. Either way, the risk sits with the buyer until vendors move beyond marketing language and into contractual obligations — a gap the press release does not bridge. [S1]
The next six months will reveal whether this is a cycle story or a structural one
Watch for three simple signals. First, whether automakers and Tier‑1s publicly reference high‑strength grades in award announcements and tooling plans — evidence that engineering choices are locking in. Second, whether public‑works procurement documents begin to name higher yield and ductility standards more consistently — a sign that code and client requirements are shifting. Third, whether mills or service centres add surcharges or allocation notices specific to advanced grades — a channel‑level indicator of tightening. If those appear, the press release’s directional claim gains credibility; if they do not, it remains a marketing artifact. [S1]